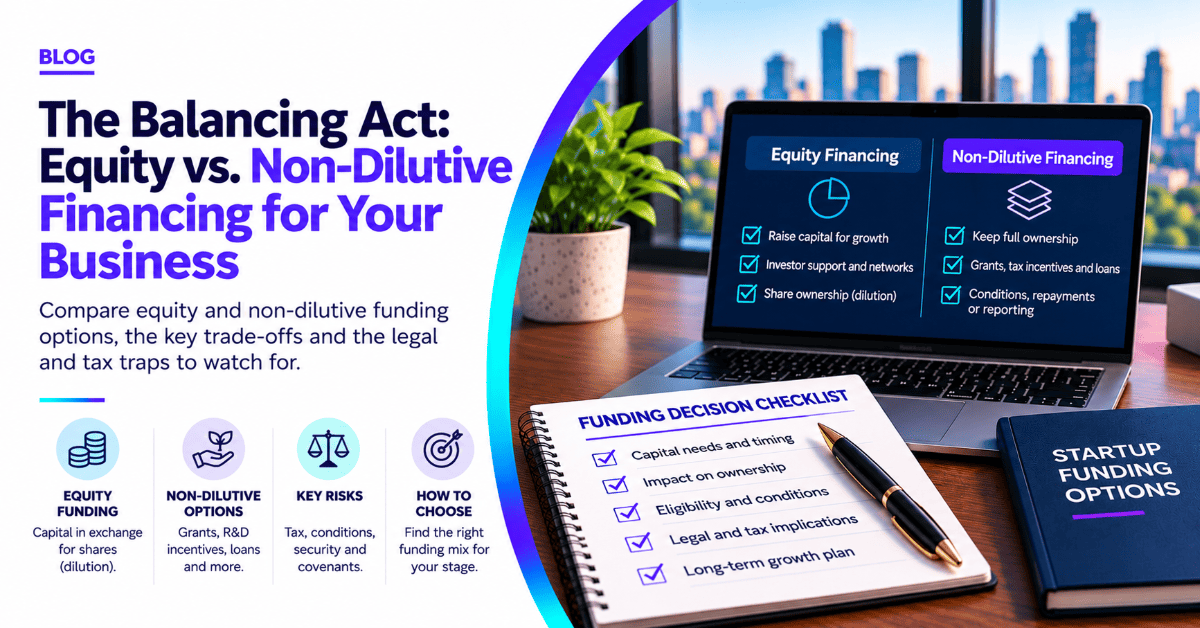
Every founder faces the same question: where will the money come from? Equity investors are one answer, but they take a share of your company. Non-dilutive funding lets you raise capital without giving up shares. Non-dilutive financing includes grants, tax incentives, loans and revenue-based products. This guide compares them with equity and explains the legal and tax traps that catch Australian founders.
What Is Non-Dilutive Funding?
Non-dilutive funding is money that does not require you to issue new shares. You keep your ownership, and your investors keep theirs. The trade-off is that the money often comes with conditions, repayments or reporting duties. Non-dilutive funding is not free funding. Founders use it to extend their runway, fund R&D and keep more shares for a later priced round.
How Equity Financing Dilutes Founders
Equity financing means selling shares to investors such as angels or venture capital funds. Each new issue of shares reduces the percentage that existing shareholders own. It does not automatically reduce the value of their shares, because that depends on the price of the round. Our guide to equity dilution in early-stage startups explains the numbers.
SAFEs and convertible notes are not non-dilutive either. They convert into shares later, so they dilute you when they convert. See our guide to SAFEs and convertible notes for how they work.
Types of Non-Dilutive Financing for Australian Startups
Government Grants
Grants fund a project without taking equity. Most require you to contribute your own cash. The Industry Growth Program’s guidelines, for example, fund up to 50% of eligible expenditure. They pay on an agreed schedule, subject to satisfactory progress, and they let the Commonwealth recover funds if you breach the grant agreement. They also expect you to own the IP from the project or hold exclusive rights to commercialise it.
The Commonwealth has paused that program to new applications. Check the Grants and programs finder for open rounds. CSIRO Kick-Start offers matched funding of $20,000 to $60,000 and accepts applications at any time. Our guide to securing grants covers the application process.
R&D Tax Incentive
The R&D Tax Incentive rewards eligible research spending. A company with turnover under $20 million receives a refundable offset equal to its corporate tax rate plus 18.5%. Larger companies receive a non-refundable offset with a premium of 8.5% or 16.5%, depending on R&D intensity. You must register your activities within 10 months after the end of your income year. If the offset exceeds your tax payable, you may receive a refund once you lodge your return.
The 2026-27 Budget announced changes from 1 July 2028, and a draft bill is out for consultation. Those changes are not law, so check the current rules before you plan around them.
Business Loans and Guarantees
Banks and non-bank lenders provide debt without taking shares. Many lenders ask for security over your assets and a guarantee from the directors. Lenders usually register their security on the Personal Property Securities Register. If you give a guarantee, you can owe the debt personally. The Banking Code of Practice requires subscribing banks to tell guarantors to seek independent legal and financial advice. Interest on borrowing that earns assessable income is generally deductible, but it is still a cost.
Venture Debt
Venture debt suits startups that have already raised equity. It often carries higher interest than a bank loan, restrictive covenants and warrants. A warrant gives the lender the right to buy shares later, so venture debt may not be fully non-dilutive.
Revenue-Based Financing
A funder advances cash, and you repay a percentage of your future revenue until you reach an agreed total. Read the repayment cap, the definition of revenue and any security or guarantee. Revenue-based financing is a repayment deal, not a use of licensing income as collateral.
Invoice Finance, Export Finance and Licensing
Invoice finance lets you sell outstanding invoices at a discount for faster cash. Export Finance Australia’s Small Business Export Loan offers $20,000 to $350,000 to eligible exporters without property security. Licensing your IP can also bring in upfront fees and royalties. That is revenue from a commercial deal, so negotiate the licence carefully. Our guide to IP assignment and licensing explains the key terms.
Legal and Tax Traps in Non-Dilutive Funding
Non-dilutive funding carries its own risks. Watch these points before you sign.
- Tax on grants. Grants are generally assessable income unless Parliament declares them non-taxable. GST depends on whether the payment is for a supply, as the ATO explains.
- Conditions in grant agreements. Check the IP ownership terms, the milestone schedule and the clawback rights.
- Security and guarantees. A lender’s security over all your assets can complicate a later equity raise. Investors will ask about it in due diligence.
- Unfair contract terms. Small business protections can apply to standard-form loan contracts. A small business has fewer than 100 employees or turnover under $10 million.
- Covenants and defaults. Missing a covenant can trigger default, even when you keep up repayments.
How to Choose Between Equity and Non-Dilutive Financing
The right mix depends on your stage. Equity often suits early companies with no revenue and high risk, because investors share that risk. Non-dilutive funding often suits companies with a funded project, predictable cash flow or eligible R&D. Many founders combine the two, using grants and tax incentives to stretch each equity round. Model the cost of each option before you commit. Also check your constitution and shareholders agreement, because some require investor consent before the company borrows. Our guide to a tailored shareholders agreement explains what these clauses cover.
Frequently Asked Questions
1. What is non-dilutive funding?
Non-dilutive funding is capital you raise without issuing new shares. It includes grants, tax incentives, loans, venture debt and revenue-based financing.
2. Is a grant free money?
No. Grants usually require matched cash funding, follow a milestone schedule and carry reporting duties. The funder can recover money if you breach the agreement. Grants are also generally taxable.
3. Is venture debt non-dilutive?
Often only partly. Venture debt commonly includes warrants, which let the lender buy shares later. Check the warrant terms before you sign.
4. Are SAFEs and convertible notes non-dilutive?
No. Both convert into shares, so they dilute existing shareholders when they convert.
5. Does the R&D Tax Incentive count as non-dilutive financing?
Yes, in effect. A refundable offset can return cash for eligible R&D without taking equity. You must register within 10 months after the end of your income year.
6. Do I need a personal guarantee for a business loan?
Often, but not always. Many lenders ask directors to guarantee a loan or give security. Get independent legal advice before you sign a guarantee.
How Allied Legal Can Help
Allied Legal advises startups on grants, fundraising and finance documents, from grant agreements to loan terms and security. Speak to our banking and finance lawyers before you sign, or contact us on 03 8691 3111 / hello@alliedlegal.com.au.
This article is provided for general information only and does not constitute legal advice. You should obtain legal advice specific to your circumstances before acting on any information contained in this article.