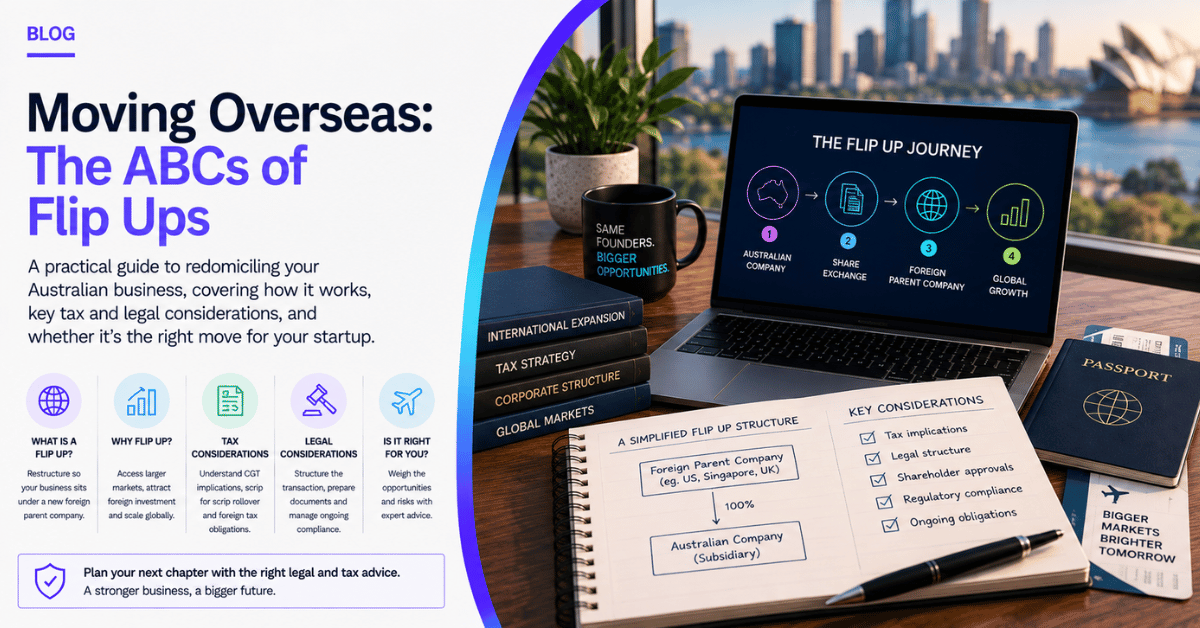
Allied Legal’s commercial and startup lawyers are regularly asked about the legal side of “flipping up”. So what is a flip up? Broadly, it means redomiciling, or put simply, restructuring so your business sits under a new company in a foreign jurisdiction.
In the startup and technology sector, that foreign jurisdiction is often the United States. This reflects its larger market, strong reputation for innovation, and relatively easy access to investment capital. These are broad generalisations, but they hold true often enough to matter. Singapore, Hong Kong and the United Kingdom are also becoming increasingly attractive destinations for the same reasons.
If you are seeking foreign investment, or your product suits a foreign market better than the Australian one, a flip up is worth considering. Foreign investors are generally far more comfortable investing in a company based in their own jurisdiction. Australia, from their perspective, is a long way away.
How a Flip Up Actually Works
A flip up is implemented by interposing a foreign company, usually a US company, between the existing Australian company and its shareholders.

From the shareholders’ perspective, shares in the Australian company are exchanged for shares in the new foreign parent company. The Australian company becomes a wholly owned subsidiary of that foreign parent. Shareholders still hold an interest in the Australian business, just indirectly, through their shares in the foreign company. In effect, the flip up moves the business to the new jurisdiction without shareholders losing their underlying stake.
Tax Considerations
Flip ups carry real tax consequences, and tax advice should be sought early rather than after the structure is already agreed.
The first question is usually whether the exchange of shares triggers an immediate capital gains tax liability for Australian resident shareholders. Scrip for scrip rollover relief can defer this in some circumstances, but it comes with real conditions: broadly, the foreign parent needs to end up owning at least 80 percent of the Australian company, and the offer needs to be available to shareholders on substantially the same terms. Even where those conditions are met, this rollover is generally only available to Australian resident shareholders. A shareholder who is already a foreign resident typically cannot rely on the same relief, since their new shares in the foreign parent will not usually remain taxable Australian property.
Moving valuable assets, including intellectual property, from the Australian company to the new foreign parent can also trigger tax consequences in its own right. A common way to manage this is for the Australian company to retain ownership of its assets and simply licence their use to the foreign company, rather than transferring ownership outright.
There are further complications to watch for, including controlled foreign company attribution rules, which can require Australian resident shareholders to include a share of the foreign company’s passive income in their own tax returns in some circumstances. On top of this, there will be foreign tax obligations in the new jurisdiction itself. Delaware is a common choice of US state for these structures, though this is mostly down to its well established corporate law and specialist Court of Chancery, rather than any special tax advantage.
Legal Considerations
A flip up raises legal issues well beyond the paperwork of moving shares. Companies should engage a lawyer early in the process to help structure the transaction and prepare the documents required to implement it. This typically includes drafting the share swap agreements that effect the exchange and establishing appropriate licensing arrangements between the Australian company and the new foreign parent.
So Should You Flip Up?
A flip up can genuinely open access to a bigger market, a deeper pool of investors, and specialist expertise that may be harder to find in Australia alone.
But these transactions are complex, expensive to implement properly, and genuinely difficult to unwind once complete. Budget for legal and tax advisors to help you get the structure right, and treat the decision as a commercial one first. Where your company sits in its own growth journey, and how much you rely on foreign capital or foreign customers, will usually determine whether flipping up makes sense for you, alongside your broader exit strategy.
If a US flip specifically is on the table, our dedicated guide to Delaware flips for Australian startups covers the state-specific detail this article does not.
Getting Started the Right Way
If you are weighing up a flip up, start with the commercial question before the structural one. First, confirm that the target foreign market or investor demand genuinely justifies the restructure. Then obtain tax and legal advice together, because both disciplines play a critical role and often overlap in a flip up transaction.Map out your full shareholder base early, including any existing foreign shareholders, since their position under the rollover rules can differ significantly from an Australian resident shareholder’s. Investing time in the groundwork before signing any documents is far less expensive than trying to fix a flip up that the parties structured incorrectly from the outset.
Frequently Asked Questions
1. What is a flip up in a startup context?
In a flip up restructure, shareholders place a foreign company above an Australian company in the corporate group. As a result, the Australian company becomes a subsidiary of the new foreign parent. Shareholders then exchange their shares in the Australian company for shares in the foreign parent.
2. Why do Australian startups flip up to the United States?
The US offers a larger market, a strong reputation for innovation, and easier access to venture capital for many startups. Singapore, Hong Kong and the United Kingdom are also increasingly common alternatives.
3. Does a flip up trigger capital gains tax for Australian shareholders?
A flip up can trigger capital gains tax consequences. However, Australian resident shareholders may be able to defer those tax consequences through scrip-for-scrip rollover relief. To qualify, they must satisfy strict requirements. These include the 80% ownership threshold and consistent offer terms for all shareholders.Foreign resident shareholders generally cannot access this relief.
4. Is Delaware chosen for flip ups mainly for tax reasons?
Not primarily. Delaware’s popularity comes mostly from its well established corporate law and specialist Court of Chancery, which gives investors legal certainty, rather than any special tax advantage over other US states.
5. Is a flip up easy to reverse if circumstances change?
No. Companies and shareholders should not treat a flip up as a quick structural fix. Implementing a flip up is complex, and unwinding one can be even more difficult. Before proceeding, they should obtain tax and legal advice and carefully consider the commercial consequences.
Need help? At Allied Legal we help startups and scale ups implement flip ups. Competent legal advice is critical to successfully implementing this kind of transaction. Call us on (03) 8691 3111 or email hello@alliedlegal.com.au.
Related Reading:
- Delaware Flips Australia: The Guide for Startups Expanding to the US
- Startup Exit Strategies: How to Prepare for IPOs and Acquisitions
Useful Resources:
This article is provided for general information only and does not constitute legal advice. You should obtain legal advice specific to your circumstances before acting on any information contained in this article.