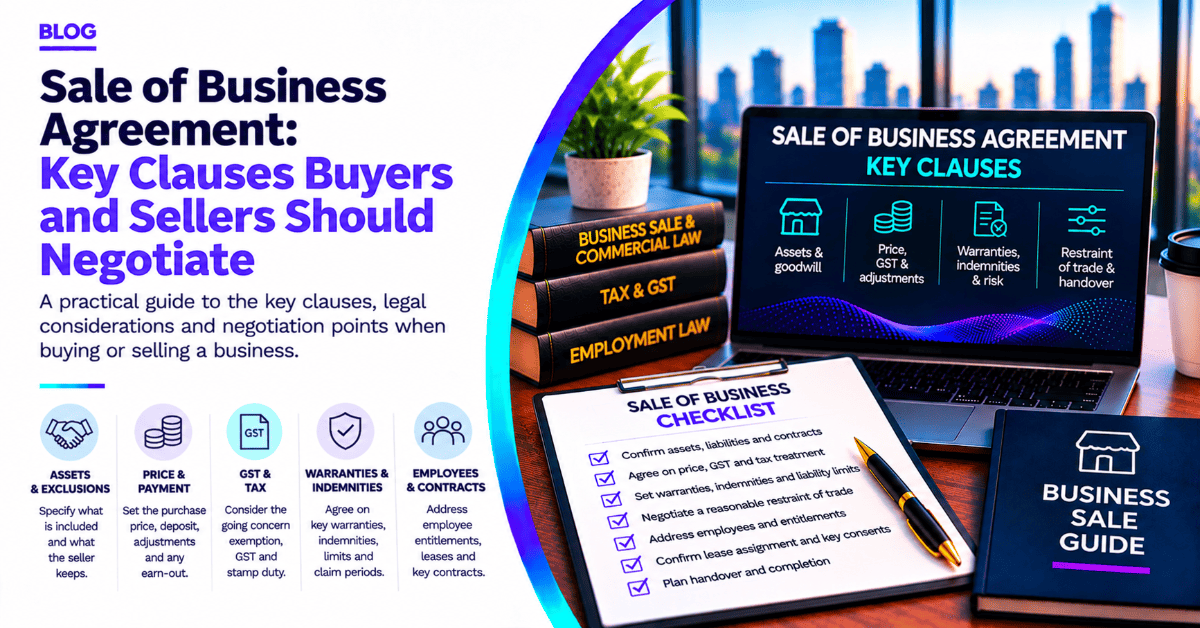
Once a buyer and seller agree on a deal, the sale of business agreement turns that handshake into binding terms. It decides what changes hands, what the buyer pays, who carries which risks and what happens if something goes wrong. Because so much rides on this one document, both sides should understand its key clauses before they sign.
This guide walks through the clauses that matter most and the points buyers and sellers usually negotiate.
What Is a Sale of Business Agreement?
A sale of business agreement is the contract that transfers a business from a seller to a buyer. It usually covers an asset sale, where the buyer takes over the business’s assets, goodwill and some contracts. If the buyer purchases the company itself, the parties use a share sale agreement instead. Our guide on buying shares or assets explains the difference.
Some states have standard form contracts for smaller business sales. In Victoria, for example, the seller of a small business must usually give the buyer a vendor statement under section 52 of the Estate Agents Act 1980 (Vic). This applies where the goodwill, plant, equipment and fittings sell for $450,000 or less, and a buyer who does not receive one may be able to end the contract. However, most deals still need tailored terms to reflect what the parties actually agreed.
Assets Included and Excluded
First, the agreement should list exactly what the buyer gets. This often includes equipment, stock, intellectual property, customer lists, the business name, website and goodwill.
Just as important is what the seller keeps. Cash, debtors, personal vehicles and certain liabilities often stay with the seller. A clear list of included and excluded assets prevents arguments at handover. If the business uses equipment under a lease or finance agreement, the agreement should also say whether the buyer takes over those arrangements or the seller pays them out.
Price and Adjustments
The agreement sets the purchase price and how the buyer will pay it. It should also explain:
- the deposit and when it becomes non-refundable
- how the parties will value stock on the completion date
- adjustments for rent, utilities and other outgoings
- any earn-out, where part of the price depends on future performance
GST and the Going Concern Exemption
GST can add 10% to the price if the parties do not plan for it. In many cases, a business sale can qualify as a GST-free supply of a going concern. According to the ATO, the conditions include that the buyer is registered or required to be registered for GST, the seller supplies everything needed for the business to keep operating, the seller carries on the business until the day of the sale, and the parties agree in writing that the sale is of a going concern. Get tax advice early, because missing a requirement can make GST payable. Depending on the state, stamp duty may also apply to some business assets, such as goodwill or land, so factor this into the price.
Conditions Precedent
Conditions precedent are steps that must happen before the sale completes. Common examples include:
- the buyer obtaining finance
- satisfactory due diligence
- the landlord consenting to a lease assignment
- third parties consenting to key contracts transferring
- licenses or permits transferring to the buyer
Each condition needs a deadline and a clear outcome if it fails. Usually, either party can then end the agreement and the buyer gets the deposit back.
Warranties and Indemnities
Warranties are promises the seller makes about the business, such as the accuracy of the accounts or the absence of disputes. If a warranty turns out to be false, the buyer may claim compensation.
Indemnities go further. An indemnity clause requires the seller to cover specific losses, such as claims arising from how the seller ran the business before completion. Sellers usually push to limit both, for example with a cap on total liability and a time limit for claims. Buyers, meanwhile, often ask to hold back part of the price to secure any claims.
Restraint of Trade
A buyer pays for goodwill, so it needs protection from the seller setting up a competing business down the road. A restraint of trade clause stops the seller from competing within a certain area and time.
However, courts only enforce restraints that are reasonable. Courts usually give more room to restraints in a business sale than in employment, because the buyer has paid for the goodwill. Even so, many agreements use a cascading restraint, with several alternative areas and periods. If a court finds the widest option unreasonable, a narrower one may still apply. In NSW, the Restraints of Trade Act 1976 also allows courts to read down an unreasonable restraint. Our article on post-employment restraints explains how courts assess reasonableness in the employment context.
Employees and Entitlements
The agreement should state which employees the buyer will offer jobs to and on what terms. It must also deal with accrued entitlements, such as annual leave and long service leave.
Under the Fair Work Act, a transfer of business usually carries a transferring employee’s past service across to the buyer. However, if the seller and buyer are not associated entities, the buyer can choose not to recognise prior service for annual leave, personal leave and redundancy. In that case, the seller usually has to pay out accrued annual leave. Long service leave is governed by state and territory laws, which usually treat service as continuous on a sale. Awards and enterprise agreements covering the employees may also transfer to the buyer. As a result, the parties often adjust the price to reflect entitlements the buyer will inherit.
The Lease and Key Contracts
Many businesses depend on their premises and a handful of important contracts. Usually, the landlord must consent before the seller can assign the lease. In many states, retail leases laws limit when a landlord can refuse consent. However, the seller and any guarantor may stay liable under the lease after assignment unless they are released. Likewise, suppliers and customers may need to consent before their contracts transfer.
The agreement should set out who must obtain each consent and what happens if a consent does not arrive in time.
Handover and Completion
Completion is when the buyer pays the balance and takes control. The agreement should list what the seller must hand over on the day, such as keys, passwords, records and signed transfer documents.
Before completion, the buyer should also search the Personal Property Securities Register and ensure the seller releases any security interests over the assets. Many agreements also require the seller to provide a training or handover period so the buyer can learn the business.
Frequently Asked Questions
1. Who prepares the sale of business agreement?
Usually, the seller’s lawyer prepares the first draft. The buyer’s lawyer then reviews it and proposes changes. Both sides should get their own legal advice.
2. Can I use a template sale of business agreement?
A template can work for a very simple sale. However, most businesses have specific assets, contracts and risks that a template will not cover. Tailored terms help avoid disputes after completion.
3. What happens if a condition precedent is not met?
The agreement usually lets either party end the contract, and the buyer gets the deposit back. Sometimes the parties agree to extend the deadline instead.
4. How long should a restraint of trade last?
It depends on the business, the industry and the value of the goodwill. Courts only enforce restraints that go no further than reasonably necessary to protect the buyer, so tailor the area and period to the deal.
How Allied Legal Can Help
Our business sale and purchase lawyers act for both buyers and sellers. We draft and negotiate sale of business agreements, advise on warranties, restraints and employee transfers, and manage the deal through to completion. If you are selling, our guide to selling a business in Australia is a useful place to start.
To discuss your sale or purchase, call us on 03 8691 3111 or email hello@alliedlegal.com.au.
This article is provided for general information only and does not constitute legal advice. You should obtain legal advice specific to your circumstances before acting on any information contained in this article.