Reverse vesting is a common term in startup investment deals. But what does it actually mean, and why do investors almost always ask for it?
This guide explains reverse vesting in plain terms. It covers how it works, why startups use it, and the tax and legal points worth getting right before you sign anything.
What Is Reverse Vesting?
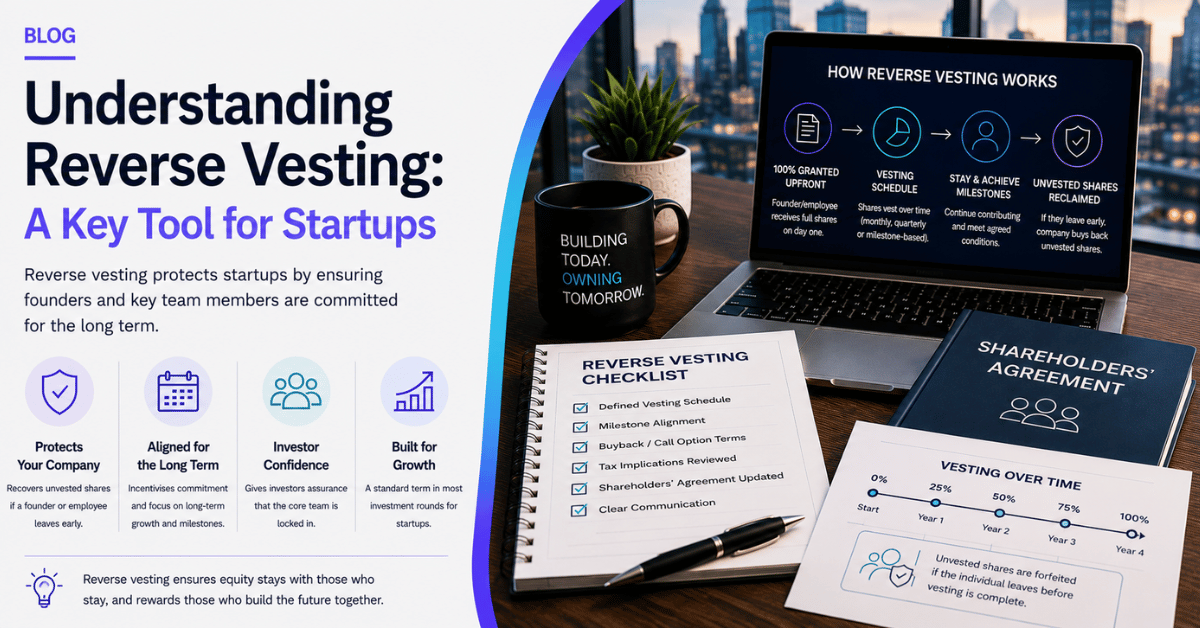
Reverse vesting means a founder or key employee gets their full share of equity upfront, on day one. But those shares start out “unvested”. The company keeps the right to buy back or cancel some or all of them if the person leaves early, or misses agreed milestones.
This protects the company from an early exit by someone who still holds a large ownership stake.
Reverse Vesting vs Regular Vesting
Regular vesting works the other way around. The recipient earns their equity gradually, a little at a time. For example, a founder might earn 2 percent of the company each year, building up to 8 percent over four years.
Reverse vesting flips this. The recipient gets 100 percent of their shares straight away. But they only keep them if they stay and meet the agreed conditions. Leave early, and the company can claw back the unvested portion.
Why Startups Use Reverse Vesting
Startups depend on key people staying engaged for the long haul. Reverse vesting protects the company if a founder or senior employee walks away early while still holding a big equity stake.
Founders do not always love reverse vesting at first. It can feel like a limit on their own shares. But in practice, it is usually the investors who insist on it, not the founders. Venture capital firms and other investors want proof that the core team is locked in for the journey. So reverse vesting is a standard term in most external investment rounds.
It also protects the founders themselves. If a co-founder leaves in year one, reverse vesting stops them walking away with a large, permanent stake in a company they no longer work on.
How Reverse Vesting Works
Reverse vesting runs on a set vesting schedule. This might be monthly, quarterly, or tied to specific milestones like a product launch or a revenue target.
If someone leaves before their schedule finishes, they forfeit the unvested portion of their shares. The company can then buy those shares back.
This buyback step needs care. Under the Corporations Act, a company generally needs shareholder approval to buy back its own shares, and the process varies depending on the type of buy-back used. Many startups instead use a call option or forfeiture clause in a shareholders’ agreement, so the unvested shares are reclaimed without running a formal buy-back process each time. Get this structured properly from the start, rather than relying on a generic template.
Tax Considerations
Tax treatment for reverse vesting shares depends on the details, including how the shares were issued and whether they fall under the Employee Share Scheme rules. It is not automatically a tax saving.
In general, tax on shares that are subject to a real risk of forfeiture is calculated later, once the shares vest, rather than upfront. That can help with cash flow, since the recipient is not paying tax on shares they might still lose. But it also means tax is worked out using the share value at the later vesting date, which is often higher than the value on day one. Get specific tax advice before assuming reverse vesting reduces your total tax bill.
Key Considerations Before You Set It Up
A few decisions matter most when putting reverse vesting in place.
- Equity allocation: too much upfront equity can create tension if someone leaves early. Too little may not motivate anyone to stay.
- Fair terms: founders and key employees should understand exactly what they are agreeing to, and the terms should be negotiated, not just imposed.
- Regular reviews: as the company and each person’s role changes, the vesting terms may need updating too.
Getting these details right early avoids painful disputes later, especially once outside investors are involved.
Reverse Vesting for Founders vs Employees
Reverse vesting shows up most often in two situations: founder shares at the time of an investment round, and equity grants to very early, senior hires. The mechanics are similar in both cases, but the starting point differs. Founders usually already hold shares before reverse vesting is applied, often at the investor’s request as a condition of the deal. Early employees are more commonly granted shares that are reverse vesting from day one, as part of their offer. Either way, the same core question applies: what happens to the unvested shares if the person leaves before their schedule is complete.
Frequently Asked Questions
1. What is reverse vesting in simple terms?
It means a founder or employee receives all their shares upfront, but the company can buy back or cancel the unvested portion if they leave early or miss agreed milestones.
2. Why do investors require reverse vesting?
Investors want confidence that founders and key employees are committed for the long term. Reverse vesting reduces the risk of someone leaving early while still holding a large ownership stake.
3. How is reverse vesting different from regular vesting?
Regular vesting builds up equity gradually over time. Reverse vesting gives the full amount upfront, but ties ongoing ownership to staying with the company and meeting the agreed conditions.
4. Does reverse vesting save on tax?
Not automatically. Tax on shares subject to a real risk of forfeiture is usually calculated at the later vesting date, based on the share value at that time, which can be higher than the value on day one. Get tailored tax advice before relying on any assumed saving.
5. Can a company always buy back unvested shares under reverse vesting?
It depends on how the arrangement is structured. A formal share buy-back under the Corporations Act usually needs shareholder approval, so many startups use a call option or forfeiture clause instead to reclaim unvested shares.
Related Reading:
- What Is Vesting and Why It Matters for Startups
- Founder Vesting Arrangements Explained
- Deciphering the ESS Start-Up Concession
Useful Resources:
Contact Allied Legal to structure your reverse vesting arrangements: (03) 8691 3111 or hello@alliedlegal.com.au.
This article is provided for general information only and does not constitute legal advice. You should obtain legal advice specific to your circumstances before acting on any information contained in this article.
Commercial Law
Key Commercial Law Issues Founders Need to Know
COMMERCIAL LAW
Starting a Business in Australia: Your Essential Guide

COMMERCIAL LAW