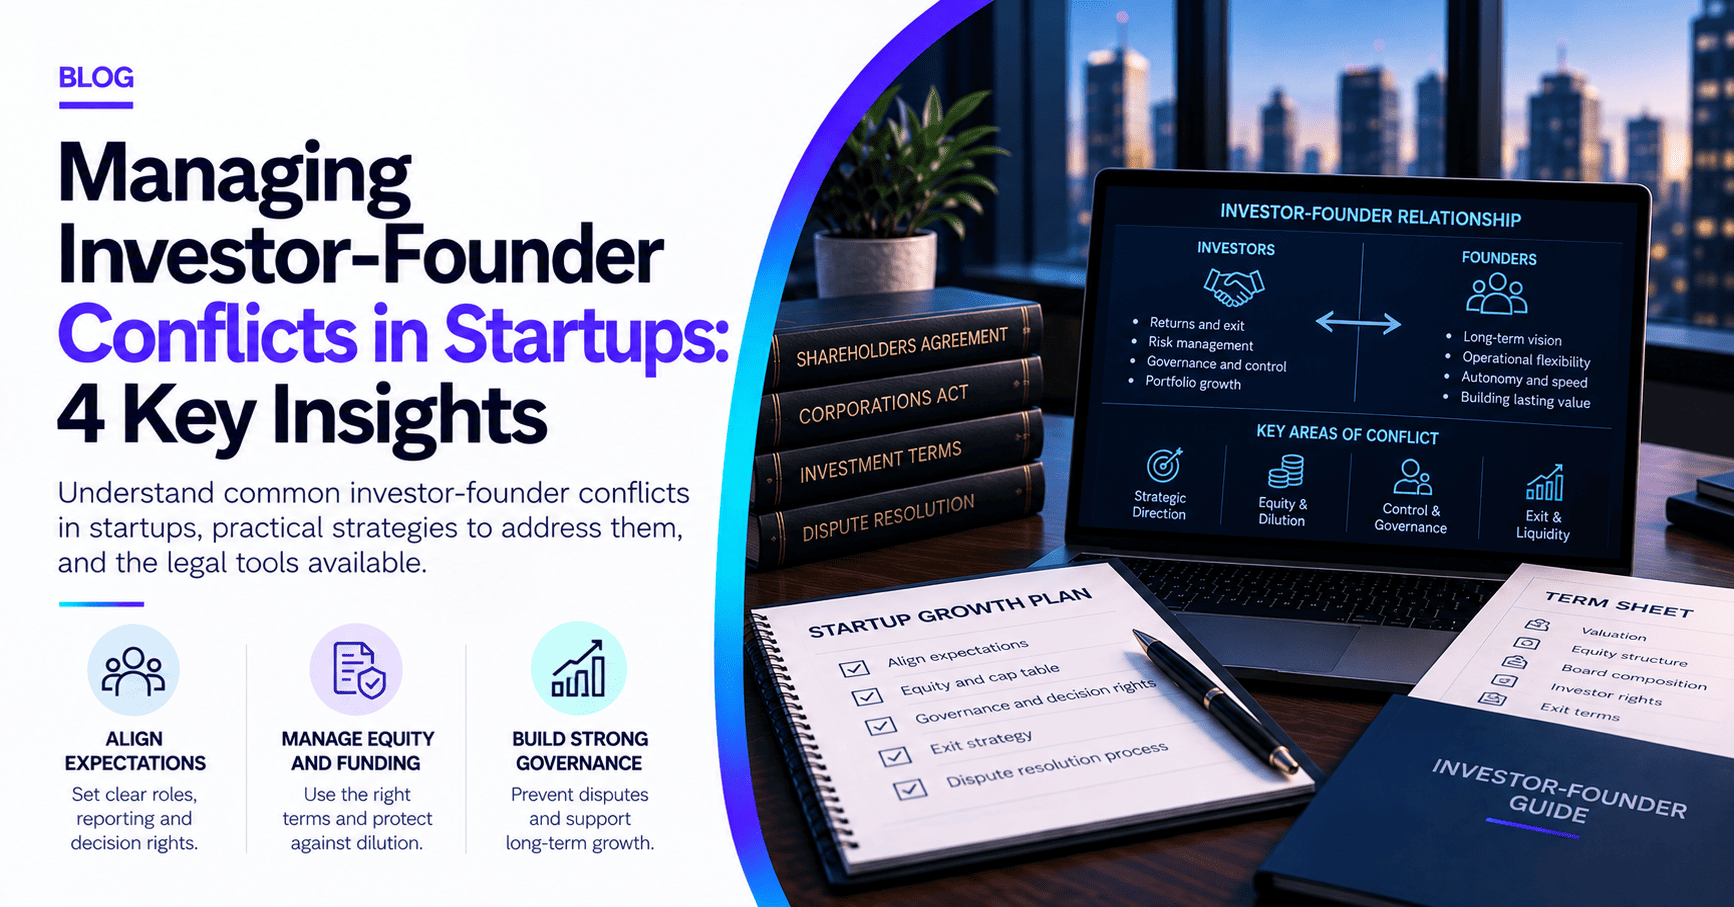
Investor-founder conflict is a common challenge in startups. Left unresolved, it can stall growth, damage relationships and end in legal disputes. These conflicts rarely appear overnight. They often start small. A founder misses a key decision, investors push for an earlier exit, or the two sides disagree about risk. This guide shares four insights from our work with Australian startups. It covers practical strategies and the legal tools available.
Misaligned Expectations: The Root of Many Conflicts
Most investor-founder disputes come from misunderstood assumptions, not bad faith. The parties often disagree about outcomes, timelines and roles. Common flashpoints include the exit horizon, growth versus profitability, founder pay, and future funding.
Consider a founder who expects to run the company independently and pivot quickly on customer feedback. The investor expects to approve every major product change. Without clear documents, both sides grow frustrated and development slows.
Several steps help. Document roles and responsibilities before the investment closes, then review them each quarter. Agree on the reporting format and frequency, such as board packs or milestone updates. Use the term sheet and the shareholders agreement to set decision-making boundaries.
Understand where the legal rights sit. Directors owe their statutory duties to the company, not to individual investors. A shareholder therefore has no general right to regular updates. Information rights usually come from the shareholders agreement, so write them in. Our guide on why you need a shareholders agreement explains what to include. Mediation can then reset expectations before tensions escalate.
Strategic Direction Disputes: Aligning Vision With Growth
Expectation gaps concern roles. Strategic disputes concern the business path itself. As a startup scales, founders and investors may disagree about whether to pivot or stay the course. They may also disagree about speed versus sustainability.
Investors often see the company as a portfolio asset. Founders see it as their life’s work. Data bridges that gap. A founder who backs a strategic choice with traction earns trust, even when the choice differs from investor preference. Useful evidence includes customer acquisition cost trends, burn improvements and unit economics.
Try these practical steps. Hold strategy sessions twice a year, separate from board meetings. Bring in a neutral adviser or mentor to facilitate hard conversations. Keep a founder advisory board, separate from your formal board, to test bold ideas early.
On the legal side, a shareholders agreement can fix the board’s composition. It can also list the “major decisions” that need a supermajority or unanimous consent. It can also include a deadlock clause, which sets steps such as escalation, mediation and expert determination. Expert determination suits valuation disputes. Sometimes the contract offers no workable way out of a deadlock. In that case, a court may order a winding up on just and equitable grounds under section 461 of the Corporations Act. That is a last resort, so build a better pathway first.
Equity, Dilution and Funding Disputes
Equity, dilution and future rounds often trigger investor-founder conflict. Founders feel over-diluted, or investors allege capital mismanagement or misleading conduct during a raise. New rounds, such as Series A or B, bring in new investors and dilute earlier holders.
Pre-emptive rights help. For proprietary companies, the Corporations Act sets a default pre-emption rule in section 254D. It is a replaceable rule, so a constitution can displace it. Most shareholders agreements spell out the right in detail. See our guide to pro rata rights. Anti-dilution protections usually sit in the terms of an investor’s preference shares.
Try these practical steps. Document pre-emptive rights, anti-dilution terms and funding rules in the shareholders agreement. Tell investors about upcoming rounds early. Require board approval for every new issue, with an agreed valuation method. Tie founder equity to milestones through vesting. Keep an up-to-date cap table and circulate financials every quarter. Our guide to shareholder dilution covers the mechanics.
If you use convertible notes, set out the interest rate, maturity date, discount, valuation cap and conversion triggers. A liquidation preference belongs to the preference shares that a note converts into, not to the note itself.
If a dispute arises, the first remedy is usually the contract. A member can also apply to the court under section 232 of the Corporations Act. The conduct must be oppressive, unfairly prejudicial or unfairly discriminatory. A noteholder generally becomes a member only when the company issues and registers shares. The oppression remedy may therefore not be available to them. Our guide to shareholder oppression explains the test.
Control, Voting Rights and Governance Conflicts
Power struggles surface in governance and voting, especially when investors seek control beyond their equity stake. Under the Corporations Act’s replaceable rules, directors manage the company, and shareholders cannot direct them. Investors therefore gain control through board seats, reserved matters, and terms in the constitution or shareholders agreement. A director the investor nominates still owes duties to the company.
Control rights that the parties agreed in writing are not automatically oppressive. The problem is ambiguity. Define voting rights, quorum and reserved matters clearly. List the matters that need investor consent, such as major hires, fundraising and strategic partnerships. Record every board and shareholder resolution.
If the parties breach their duties or agreement, the remedies differ. A breach of the shareholders agreement is a contract claim. A breach of a director’s duty belongs to the company. ASIC can enforce it, and a member can sue on the company’s behalf with the court’s leave. In one matter we saw, a hiring dispute ended when the parties simply documented which decisions needed investor consent. Our guide to types of director disputes explains more.
Exit and Liquidity: The Disagreement to Plan For
Exit strategy is a frequent source of tension, especially in later rounds such as Series C or D. Investors may want a faster return, while founders may hold out for a higher valuation or a strategic buyer. Without pre-agreed exit terms, these conflicts can become formal disputes.
Address exits when you raise. Include drag-along and tag-along rights, and agree on realistic timelines. Our guide to the exit clause in a shareholders agreement explains these tools.
When Mediation and Court Become Necessary
Most conflicts should settle early. Mediation is usually the best first step, and courts expect it. The Supreme Court of Victoria’s oppression proceeding program builds in early mediation. The Federal Court expects parties to consider alternative dispute resolution too. Even if you never litigate, a clear paper trail strengthens your position. Our guide to resolving co-founder disputes shows how to start.
Frequently Asked Questions
1. What causes investor-founder conflict in startups?
Most conflicts come from misaligned expectations about exits, strategy, dilution, control and roles. Disagreements over funding rounds and decision-making power are also common.
2. Can an investor force a founder to share information?
There is no general right to regular updates. Directors owe their duties to the company. Investors usually get information rights through the shareholders agreement, so negotiate them before you invest.
3. What is a deadlock clause?
A deadlock clause sets steps for a decision that the parties cannot agree on. Typical steps are escalation, mediation and expert determination. It keeps the company moving when the board or shareholders are split.
4. What is the oppression remedy?
Section 232 of the Corporations Act lets a member apply to the court about conduct that is oppressive, unfairly prejudicial or unfairly discriminatory. The court can order a share buy-out or regulate the company’s affairs.
5. Do convertible note holders have oppression rights?
Generally not until they hold registered shares. The oppression remedy is for members, so noteholders usually rely on their contract.
6. What are drag-along and tag-along rights?
A drag-along right lets majority holders require others to sell in a sale of the company. A tag-along right lets minority holders join a sale on the same terms.
7. Should we use mediation before going to court?
Usually, yes. Mediation is quicker and cheaper, and it protects the relationship. Courts also expect parties to consider it.
Our team advises founders and investors on shareholders agreements, reserved matters and exit terms before conflict starts. If a dispute has already begun, our shareholder dispute lawyers and dispute resolution team can step in. We review the agreements, assess the remedies, and run mediation or court action when needed. We also act in equity disputes arising from capital raisings. Call us on 03 8691 3111 or email hello@alliedlegal.com.au to get advice before the conflict escalates.
This article is provided for general information only and does not constitute legal advice. You should obtain legal advice specific to your circumstances before acting on any information contained in this article.