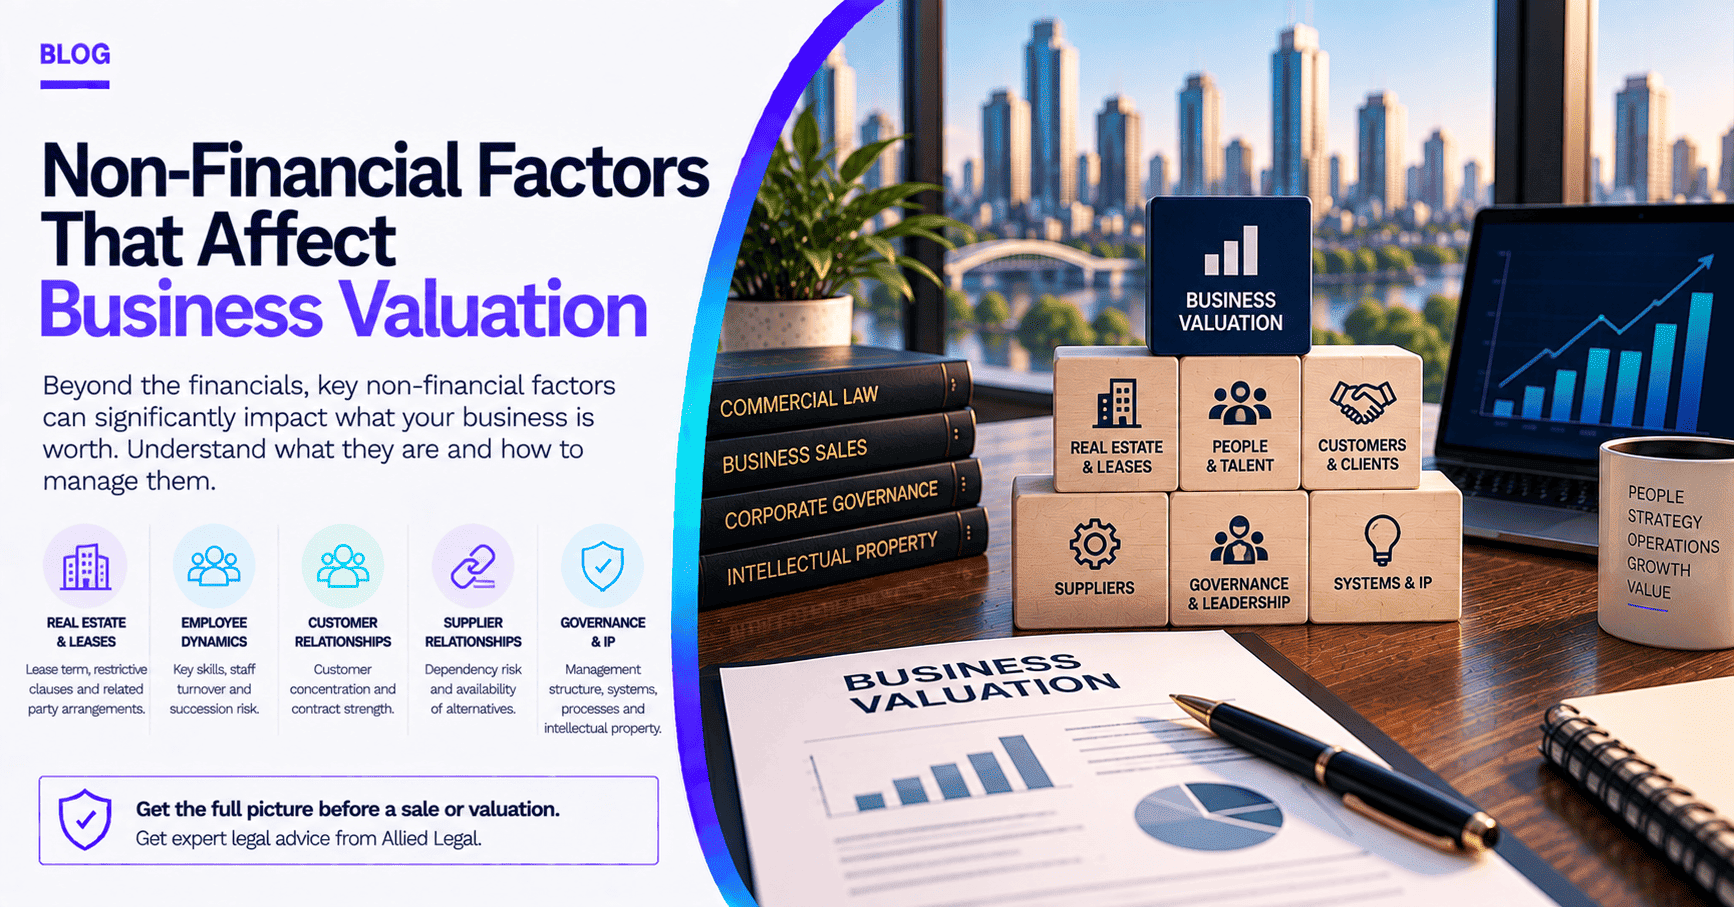
A business valuation works like a compass. It gives a business direction by putting a dollar figure on what it is worth. Valuations get prepared for different reasons, including court proceedings, lenders, tax authorities, or internal planning. The method used can flex to suit the purpose. A company’s financial performance obviously matters most to that figure. However, the business landscape is not one-dimensional. Several non-financial factors can meaningfully shift what a business is worth. Mismanaging them can drag a valuation down. In serious cases, it can tip a business toward real financial distress.
Leasing Real Estate
A business’s lease arrangements directly shape its risk profile, and its value along with it. Three things matter most here. The remaining lease term is the first. A short lease term threatens future operations.
It may force a costly relocation, which can reduce a business’s value. Restrictive clauses are the second. A demolition clause is a good example. A landlord can only end a lease early for demolition under the Retail Leases Act 1994 (NSW) and its Victorian equivalent if it has a genuine demolition proposal. It must also give the tenant at least six months’ notice. That notice period helps, and so does the fit-out cost reimbursement that sometimes comes with it. Neither fully offsets the disruption of losing the premises.
A demolition clause still represents real risk worth pricing in. Related party arrangements are the third. If a business leases property from a related party, the rent needs to reflect market terms. The ATO can treat underpriced rent between a private company and a shareholder or associate as a deemed dividend. This falls under Division 7A of the Income Tax Assessment Act 1936 (Cth). Any deviation from market rent needs a proper commercial justification. Our guide on commercial lease review covers what to check in your own lease before a sale or valuation process begins.
Employee Dynamics
A business’s people can move its value just as much as its lease. Roles and responsibilities matter first. Unique skills matter here, along with a genuine degree of cross-training. This is especially true among managers and team leaders. Good cross-training reduces the business’s dependence on any one person. Exit risk matters second. High staff turnover, an ageing team, or limited career progression can all point to a value reduction. Valuers formally recognise over-reliance on key people as “key person risk.” A business with heavy dependence on one or two individuals attracts a discount for this. Losing that person puts real continuity at risk.
Customer and Client Relationships
A business’s customer base, and how it is contracted, affects value in a similar way. Customer spread is the first issue. Relying on a few major customers for most of a business’s revenue concentrates risk. This usually reduces value. The strength of the underlying relationship is the second issue. A contract-based relationship generally carries less risk than one built on an informal, purely personal connection. Each case still needs assessing on its own facts. Our article on improving customer relationships with clear contracts covers how to put those relationships on a more solid footing.
Supplier Relationships
The same concentration risk applies on the supply side. A business that depends on one or two key suppliers faces real exposure. This is especially true where no real alternatives exist. That exposure gets priced into the business’s value. A buyer or financier will discount for supply disruption risk they cannot easily control.
Director and Shareholder Impact
How involved directors and shareholders are in the business also matters. A business that relies heavily on one or two key individuals to function day to day often attracts a lower valuation. A business with a genuinely strong management structure underneath its owners can attract a premium instead. This connects directly to how well governance works at board level. Our guide on directors’ duties covers what directors need to get right. Our corporate governance service can help structure a board that reduces this kind of key person exposure.
Systems, Processes, and Intellectual Property
How well a business documents its own operations matters too. A business built on clear, written systems and processes can run without its owner in the room. That reduces key person risk across the whole business, not just at the leadership level. Properly protected intellectual property adds a similar benefit. Registered trade marks, documented know-how, and clear ownership of software or branding all make a business easier to transfer to a new owner. A buyer pays less for a business built entirely around one person’s personal relationships and undocumented knowledge. Our intellectual property team can help you get this properly protected and documented well before a sale process starts.
Getting the Full Picture Before a Sale or Valuation
A business valuation is not just about the numbers on a balance sheet. It is also about the people, relationships, and structures underneath those numbers. A comprehensive valuation accounts for all of this. It should reflect a business’s actual, holistic worth, not just its financial statements. This matters most when you are actually buying or selling a business. An accurate valuation underpins the whole negotiation at that point. Our business sale and purchase team can help you get the legal side of that process right, alongside the valuation itself.
Frequently Asked Questions
1. What are non-financial factors in a business valuation?
They are the factors beyond a company’s financial statements that still affect what it is worth. This includes lease terms, key employee and customer concentration, supplier dependence, and how involved directors and shareholders are.
2. Can a lease affect how much a business is worth?
Yes. A short remaining lease term, a demolition clause, or below-market rent paid to a related party can all introduce risk. That risk tends to reduce a business’s value.
3. What is key person risk in a business valuation?
It is the risk that a business depends heavily on one or two individuals, such as a director, manager, or key employee. Valuers apply a discount for this, since losing that person puts the business’s continuity at risk.
4. Does customer concentration reduce business value?
Yes. Relying on a few major customers for most of a business’s revenue concentrates risk. This typically reduces value, especially where the relationship is informal rather than contract-based.
5. Why does related party rent need to reflect market value?
Underpriced rent between a private company and a shareholder or associate can be treated as a deemed dividend. This falls under Division 7A of the Income Tax Assessment Act 1936 (Cth), so it needs a genuine commercial justification.
6. Should non-financial factors be reviewed before selling a business?
Yes. A buyer or valuer will usually account for these risks regardless. Reviewing lease terms, key contracts, and governance structure beforehand helps avoid a lower valuation or a difficult negotiation.
Getting a business ready for sale, investment, or an accurate valuation takes more than good financials. Our team at Allied Legal reviews the legal risks sitting behind a valuation. This covers lease terms, related party arrangements, customer contracts, and governance structure. We help you identify and manage the non-financial risks that can quietly erode a business’s value. This matters well before a buyer or valuer finds them first. Contact us at 03 8691 3111 or email hello@alliedlegal.com.au to get your business’s non-financial risk profile reviewed properly.
This article is provided for general information only and does not constitute legal advice. You should obtain legal advice specific to your circumstances before acting on any information contained in this article.